Your VA benefit works after the purchase too
Ad Copy
Most veterans use their VA home loan benefit exactly once — the day they buy. Then it sits there. It's not a one-time coupon. The same benefit lets you refinance that home two ways: • VA Cash-Out — replace your current mortgage with a new one and take the difference in cash. Fixed rate, no PMI, VA-capped lender fees. • VA IRRRL — if your existing VA rate is meaningfully higher than today's, drop it with a streamlined process. Often no appraisal, usually no income docs. Not sure which one fits? That's the normal answer. Run your numbers (60 seconds, no credit check to see options) and a VA loan specialist — one person, not a call center — calls within 24 hours to walk through both. If neither makes sense right now, they'll say so. Run my numbers → Servbank, N.A. NMLS #203463 · Equal Housing Lender. Servbank is a VA-approved lender and is not affiliated with or endorsed by the U.S. Department of Veterans Affairs. Not a commitment to lend. All loans subject to credit and underwriting approval. Rates, terms and program availability subject to change. Cash-out amount depends on home value, existing loan balance, credit and appraisal. VA IRRRL requires an existing VA loan, a net tangible benefit, six consecutive on-time payments and at least 210 days since the first payment due date; appraisal and income documentation are typically not required but may be requested.
More from Viribuz Legal Network
Stayed On Camp Lejeune? Submit A Claim Today -->
Viribuz Legal Network
Stayed On Camp Lejeune? Submit A Claim Today -->
Viribuz Legal Network
The US Government Owes Money
Viribuz Legal Network
Stayed On Camp Lejeune? Submit A Claim Today -->
Viribuz Legal Network
Stayed On Camp Lejeune? Submit A Claim Today -->
Viribuz Legal Network
Stayed On Camp Lejeune? Submit A Claim Today -->
Viribuz Legal Network
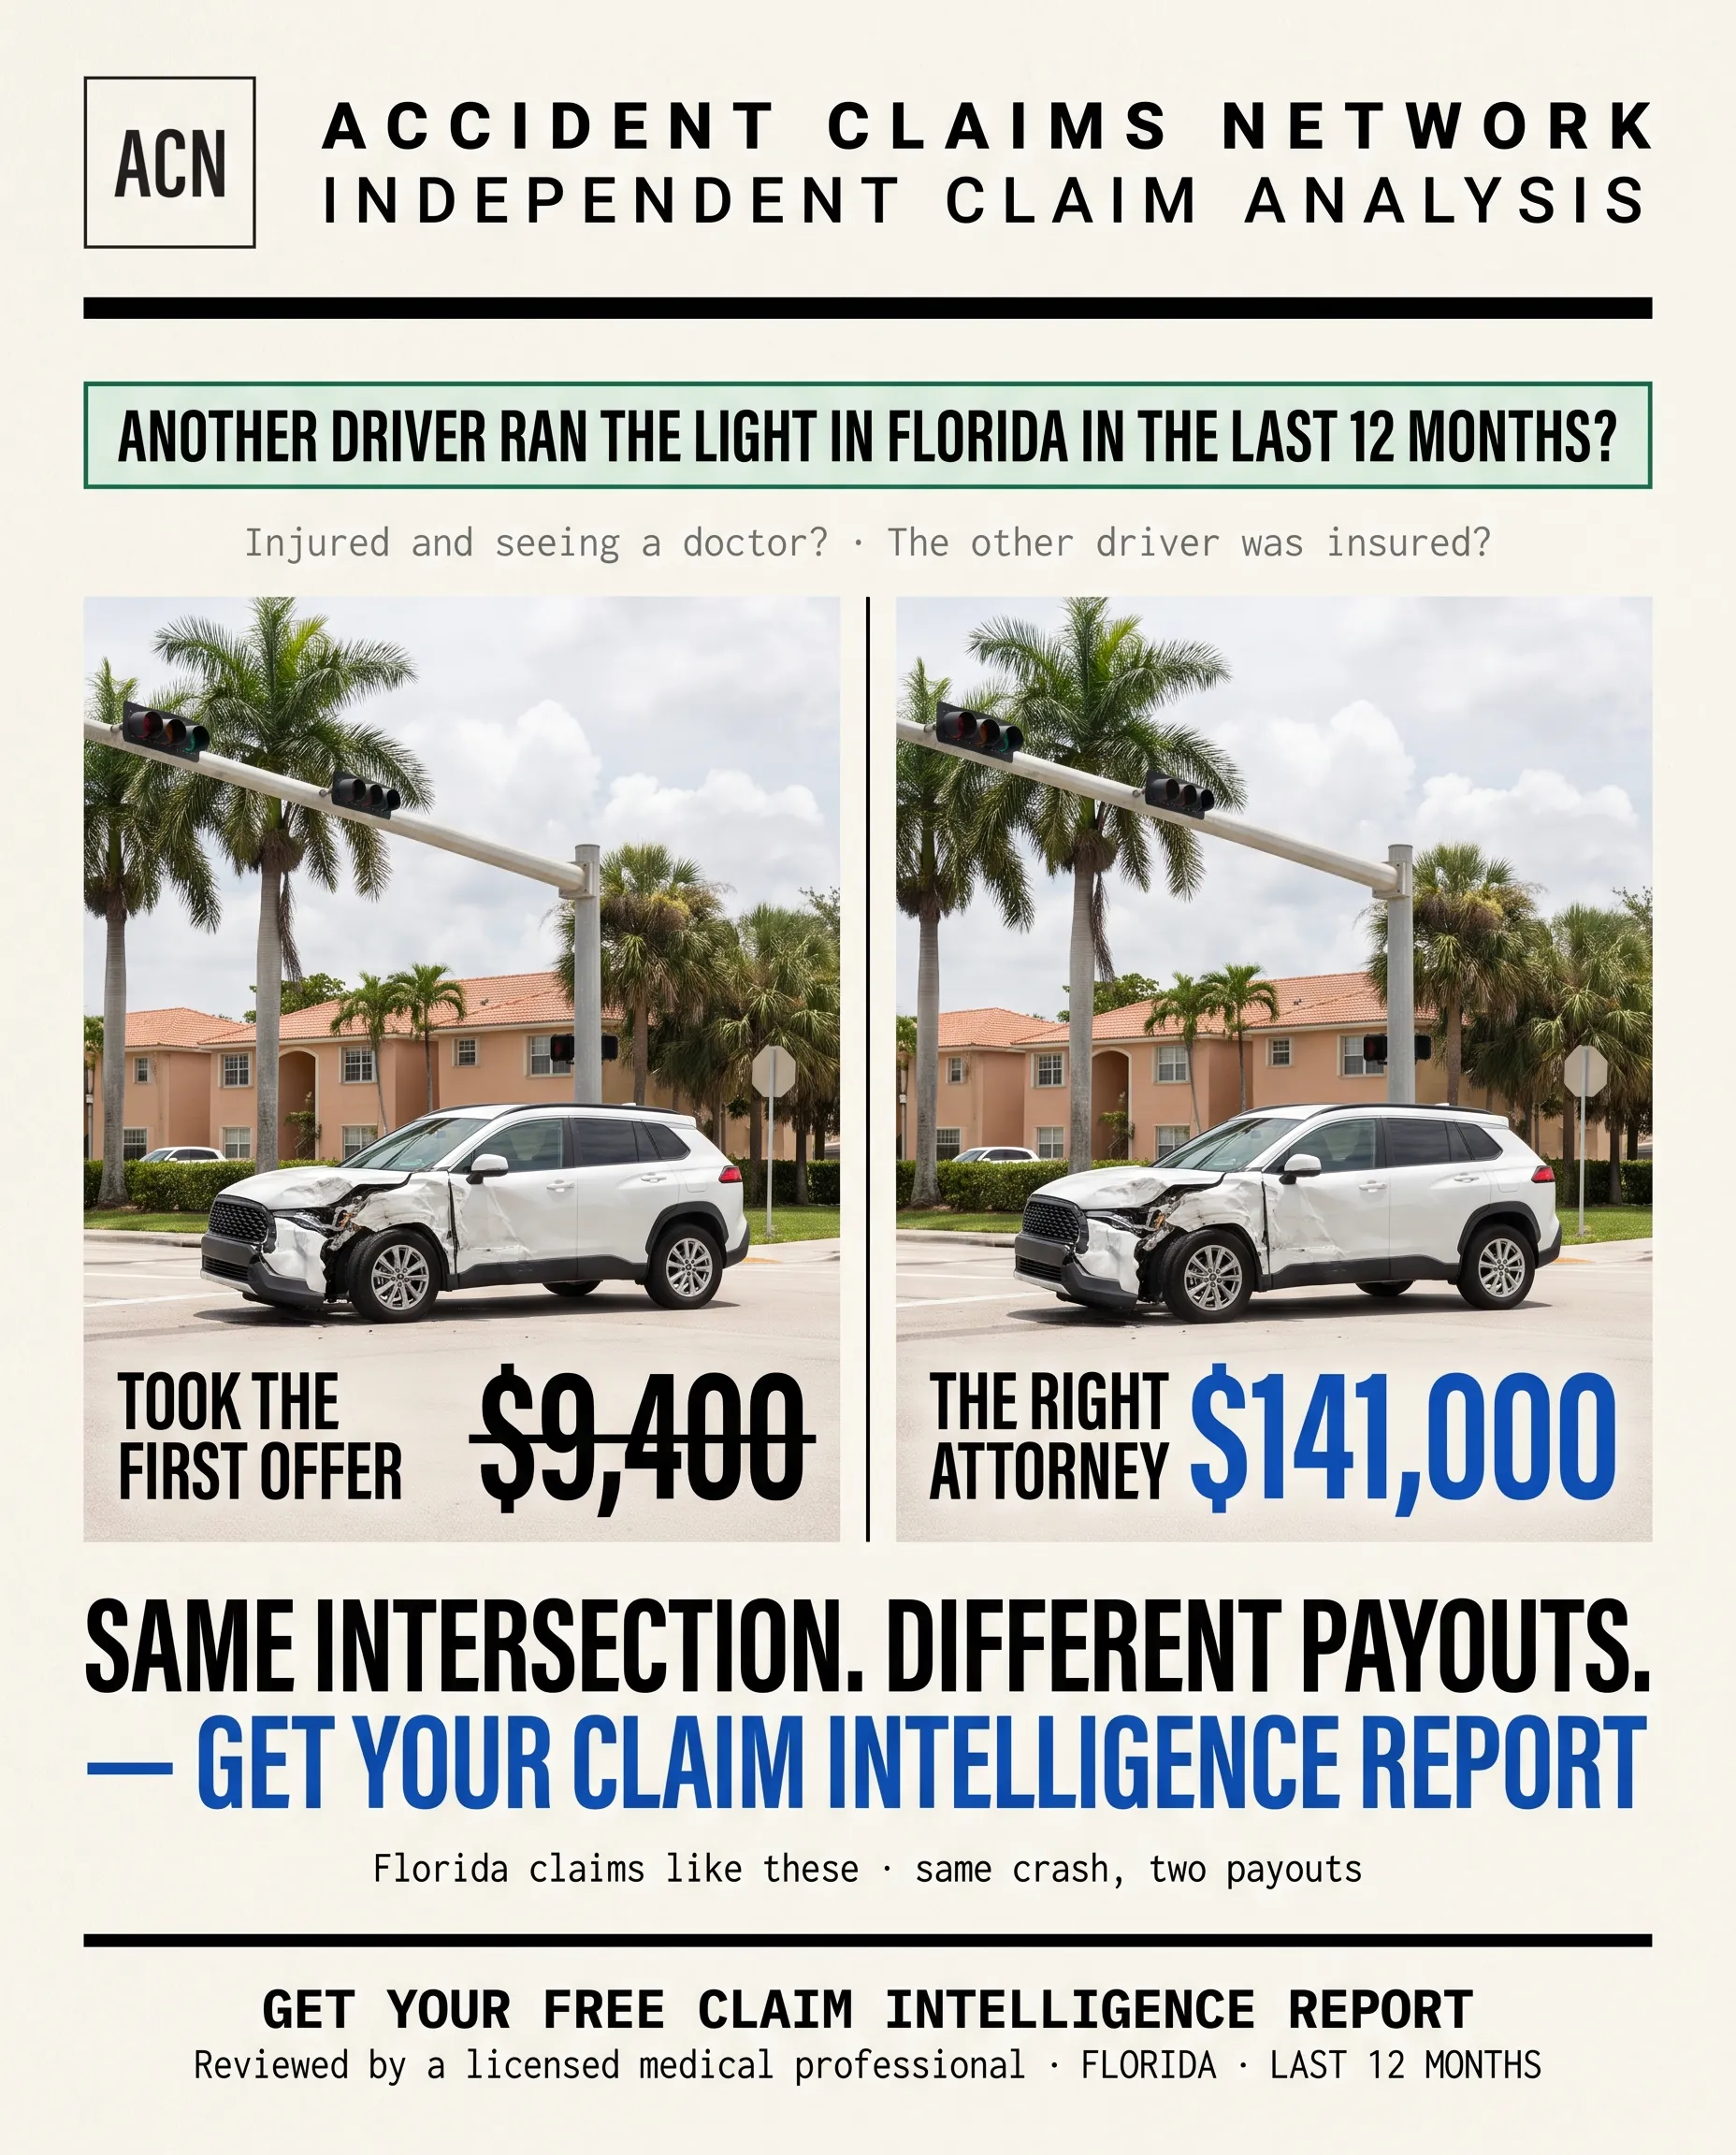
Get your Florida Claim Intelligence Report — free
Viribuz Legal Network
Unlock up to $200K in home equity
Viribuz Legal Network
Roll high-interest balances into one fixed payment
Viribuz Legal Network
Hit on your motorcycle? Get your version on paper.
Viribuz Legal Network
Hit on your motorcycle? Get your version on paper.
Viribuz Legal Network
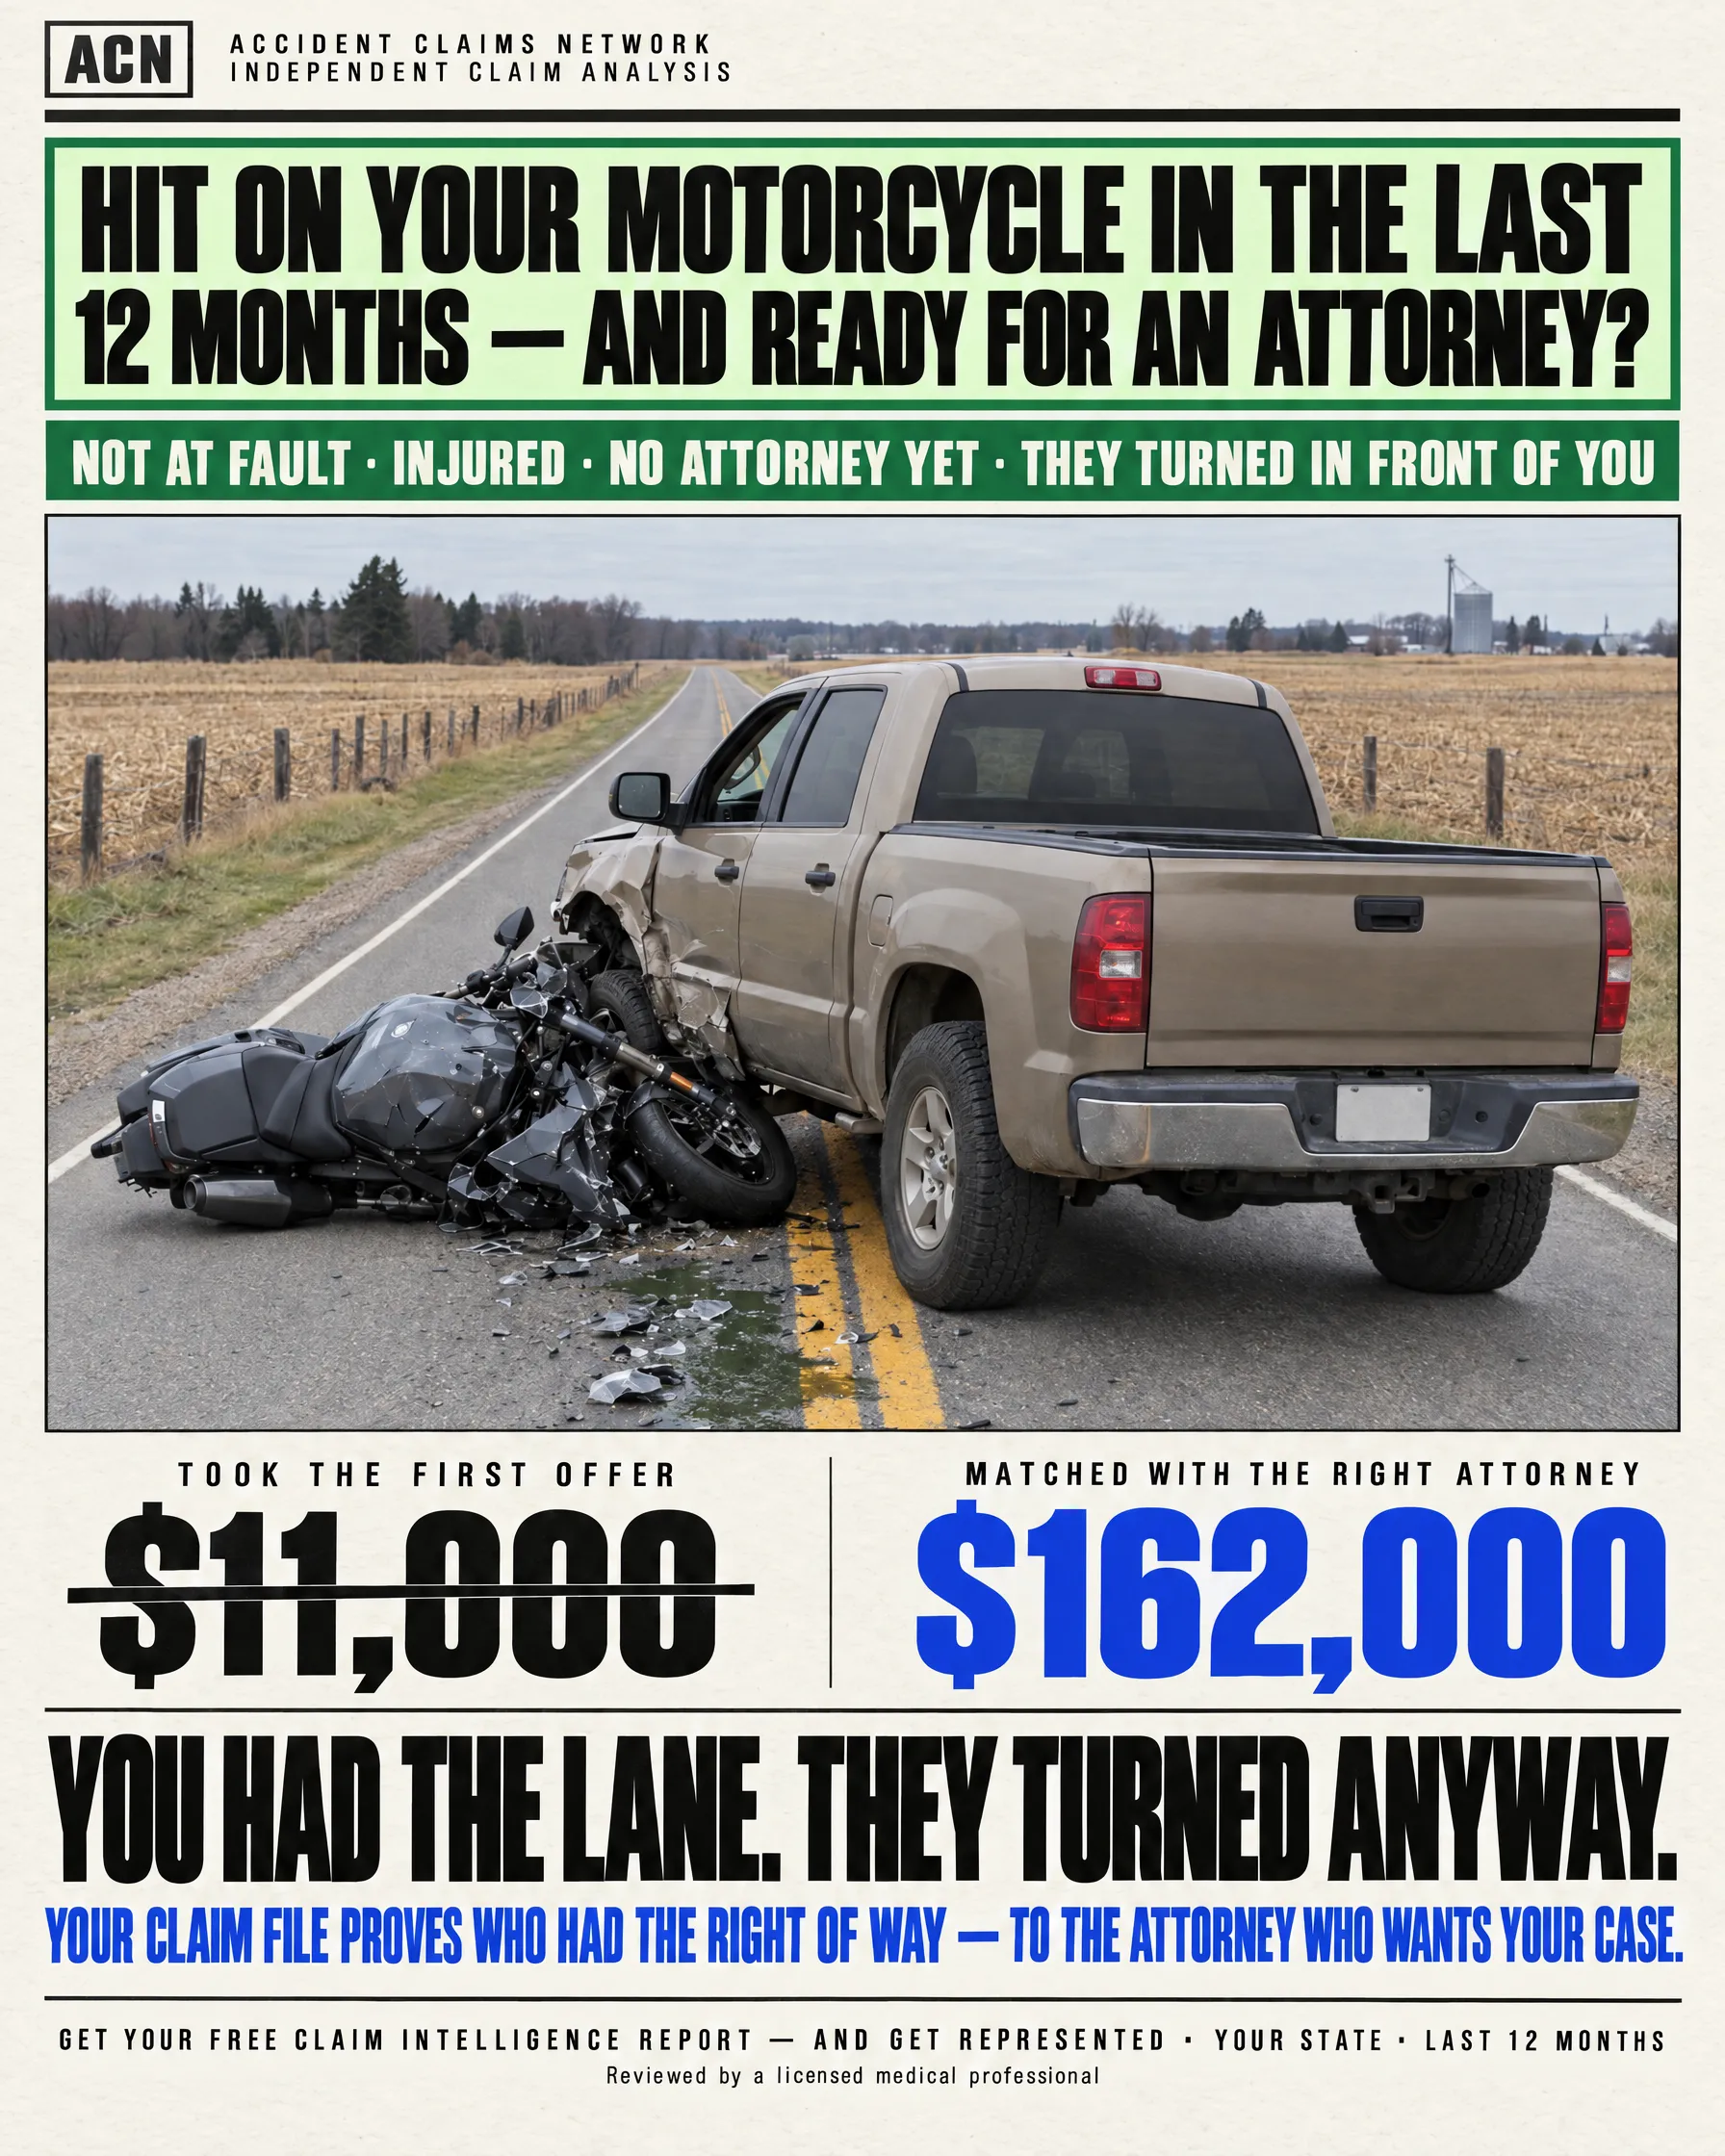
Hit on your motorcycle? Get your version on paper.
Viribuz Legal Network
 Add to Chrome